October 2026 Housing Market Report: The Cost of Overpricing


- The Penalty for Overpricing: Sellers were forced to cut asking prices on over 3,000 properties a day in September, the highest level in 15 years. The average price reduction was nearly 7%.
- Recovery Delayed to 2028: Savills forecasts that the UK housing market will not meaningfully recover until the second half of 2028, predicting a 1.5% national price fall next year as global conflicts push back mortgage rate relief.
- First-Time Buyer Squeeze: Hamptons data reveals that most first-time buyers are now paying an extra £39 per month on their mortgage than they did in rent.
- The Regional Divide: While the North of England is forecast to see 1% growth next year, London and the South East are braced for a 3.5% decline, heavily influenced by the continued depreciation of leasehold flats.
- Growth Stalls Again: Nationwide data confirms that annual house price growth slowed to 0.5% in October, its weakest level since January 2024, while Lloyds reported that British house prices were flat in September.
- Base rate set to increase: The Bank of England is widely expected to raise the base rate from 3.75% to 4% this Thursday in response to UK inflation hitting 3.5% and the recent 3.6% rise in the Ofgem energy price cap.
The UK property market is currently defined by a stark gap between seller expectations and buyer affordability. Data from Rightmove reveals that asking prices for UK homes increased by just £3,500 (1%) month-on-month in October, reaching a national average of £371,015. On an annual basis, asking prices are actually slightly lower than this time last year.
This aspirational pricing is colliding with a harsh economic reality. British house prices were completely flat in September after recording their first annual fall since 2023 in August, according to Lloyds' latest housing index. This stagnation continued into October, with Nationwide reporting that average home values were broadly unchanged at £273,566 following a 0.3% decline in September. Annual house price growth has now slowed to just 0.5%, its weakest pace of growth since January 2024.
The penalty for testing the market with an inflated asking price is severe. In data shared with the BBC, Rightmove confirmed that sellers were forced to cut asking prices on more than 3,000 properties a day on average during September, the highest volume seen in 15 years. The average price reduction was nearly 7%. Crucially, homes that required a price reduction typically took 119 days to find a buyer, compared with just 39 days for those listed at a realistic price.
The property market has slowed due to economic uncertainty, rising energy prices and expectations of higher interest rates, which have pushed up mortgage costs. While housing activity is likely to remain weak in the near term, the market is expected to recover once energy-related inflation pressures ease, and consumer confidence improves.
Source: Robert Gardner, Chief Economist at Nationwide Building Society
What happened in the Budget?
Chancellor John Healey's Autumn Budget delivered a mixed bag for the housing market, confirming significant new policies while simultaneously ignoring stark warnings from property professionals regarding the "Your First Home" scheme.
The "Your First Home" Scheme
The Chancellor confirmed that £4.7 billion has been allocated to the "Your First Home" scheme, designed to assist roughly 70,000 first-time buyers over the next five years. As anticipated, the scheme will allow buyers to purchase with just a 2.5% deposit, supported by a 20% government equity loan that is interest-free for the first five years.
Crucially, however, the Treasury has restricted this scheme entirely to new-build homes, effectively ignoring SAM Conveyancing's campaign to open the initiative to the secondhand market. By locking buyers into new developments, the government risks instantly reviving the artificial 40% new-build premium trap seen under Help to Buy. Furthermore, the scheme will not officially launch until April 2027, which analysts warn could cause a short-term freeze in the entry-level market as buyers delay their purchases.
The reality of this scheme is that it is a good idea, but limiting it only to new builds is going to push up the sale price for new builds; a price that, as it stands, is an average of £396,889 in England & Wales, or £475,340 in London. This means that unless the Government reviews the scheme's use limit, first-time buyers will struggle to use it in the nation's capital.
LAD Bible: Expert warns new 2.5% deposit scheme is a 'trap' for first-time buyers
"While a 2.5% deposit sounds like the ultimate lifeline for young renters desperate to get on the ladder, restricting this scheme entirely to new-builds is a dangerous trap. Our data shows buyers are already paying a 40% premium for new developments. The Chancellor has effectively handed a £4.7 billion taxpayer subsidy straight to volume housebuilders, while leaving first-time buyers carrying the risk of immediate negative equity."
Andrew Boast FMAAT, CEO of SAM Conveyancing
Stamp Duty and Savings
Despite heavy industry lobbying, the Chancellor did not announce any permanent Stamp Duty Land Tax (SDLT) relief for first-time buyers. Instead, the government revealed plans for a new "First Time Buyer ISA" to eventually replace the current Lifetime ISA (LISA), which will notably remove the punitive 25% withdrawal charge. However, this product is not expected to launch until April 2029.
The new First Time Buyer ISA
Despite heavy industry lobbying, the Chancellor did not announce any permanent Stamp Duty Land Tax (SDLT) relief for first-time buyers. Instead, the government revealed plans for a new "First Time Buyer ISA" designed to eventually replace the current Lifetime ISA (LISA).
The standout feature of this new savings vehicle is the removal of the punitive 25% withdrawal charge. Under the current LISA rules, savers who need to access their own money for emergencies or are forced to buy a property above the outdated £450,000 price cap are heavily penalised. While the removal of this penalty is a massive win for consumer fairness, there is a significant catch: the new ISA is not expected to launch until April 2029.
This prolonged delay means prospective buyers are left navigating the flawed LISA system for another two and a half years, with no immediate SDLT relief to ease their upfront transaction costs.
Landlord Penalties
The Budget actively squeezed property investors. The income tax surcharge on property income will double from 2% to 4% starting in the 2027-28 tax year. Property experts warn this margin compression will further test landlord resolve following the Renters' Rights Act, likely triggering a sell-off that restricts rental supply and drives up tenant costs.
At SAM Conveyancing, we are already seeing landlords reacting to this:
- Tax saving using a deed: Landlords are assigning their rental income to their spouses to use their lower income tax rates. We handle this work by drafting a deed and using the HMRC Form 17.
- Transferring into a company name: The new tax affects private landlords, but not companies. Landlords look to transfer their property into a company name to benefit from this, and the other allowable deductions a company can apply to reduce their tax bill.
- Exiting the market: Some of our clients are exiting the landlord market because when they work out the benefit, they are in fact paying for their tenant to live in the property and making no money.
The Telegraph: I'm exactly who Labour's 'Your First Home' scheme is for - but it's a trap
"Britain does not just have a shortage of new houses; the entire property ladder is completely seized up. Pumping public cash exclusively into brand-new estates lines the pockets of big building firms, while everyday sellers who bought starter homes years ago are left stranded. If Chancellor John Healey genuinely wants to get Britain moving, he should let first-time buyers use this scheme on any property they choose."
Andrew Boast FMAAT, CEO of SAM Conveyancing
Devolution for Housing
Following through on Prime Minister Andy Burnham's decentralised housing strategy, a fiscal devolution roadmap was published. Mayors will receive 20% of business rates revenue from 2027/28 and a direct share of basic rate of income tax revenue in their areas from 2028/29 to fund regional housing and infrastructure projects.
Sources: Savills Research, House of Commons Library, and MoneySavingExpert
Where is the opportunity in today's market?
While the market absorbs high stock levels and stubborn borrowing costs, pragmatic home buyers can still find distinct tactical advantages:
- Aggressive Negotiators: With sellers cutting prices on 3,000 properties a day by an average of 7%, chain-free buyers hold immense leverage to demand heavy discounts from fatigued vendors whose homes have sat unsold for upwards of 119 days.
- Up-Sizers: With property listings remaining high and buyer appetite dampened by rates, those moving up the ladder have maximum choice and the negotiating power to demand realistic pricing from vendors eager to complete before year-end.
- Cash Buyers & Investors: With flat values actively dropping and leasehold transactions stalling, cash buyers immune to strict lender stress tests hold unprecedented leverage to negotiate discounts on urban apartments.
Sources: Rightmove, Nationwide, and BBC News
Property prices and sales volumes
England & Wales
The latest Land Registry data confirms that transacted values have slowed to a crawl beneath the weight of high borrowing costs. In August 2026, the average property price in England & Wales stood at £288,411, representing a very modest 0.5% year-on-year increase from August 2025 (£286,839).
The average price for first-time buyers reached £242,014, up just 0.7% annually. Meanwhile, owner-occupiers purchased at an average of £350,739 (up 0.5%), and cash buyers at £274,435 (up 0.2%).
Beneath the national figures lies a pronounced geographic divergence. Commuter belts on the periphery of northern hubs continue to see asking prices rise, driven by buyers seeking value away from southern price caps. Looking ahead, Savills forecasts this trend will accelerate, with the North of England and Scotland expected to grow by 1% next year.
Mortgage Rates
Residential mortgage interest rates for September 2026 confirm the reality on the ground for borrowers: refinancing remains a significant financial hurdle. The baseline rule of the current property market is simple: mortgage rates at this elevated level dictate that house prices must fall to maintain buyer affordability. This friction is severely compressing the onward purchasing power of existing homeowners, meaning those looking to trade up the property ladder must heavily subsidise their move by driving a hard bargain on their onward purchase.
For those looking to secure new borrowing, the recent spike in wholesale swap rates means high street lenders are actively pulling their most competitive fixed products. Borrowers are strongly advised to lock in formal offers immediately to protect their purchasing budgets against further repricing.
Right now, if asked whether to secure a 2- or 5-year fixed deal, the answer would have to be 2 years in the hope that by 2028 inflation is under better control and the base rate is closer to 3%.
| Mortgage Product | September 2026 | August 2026 | September 2025 |
|---|---|---|---|
| 2 Year Fixed (75% LTV) | 5.13% | 4.92% | 4.19% |
| 2 Year Fixed (90% LTV) | 5.37% | 5.16% | 4.58% |
| 5 Year Fixed (75% LTV) | 4.98% | 4.78% | 4.16% |
| 5 Year Fixed (90% LTV) | 5.17% | 4.95% | 4.51% |
Sources: Financial Times and Bank of England
Will mortgage rates go down in winter 2026?
Any remaining optimism for a winter rate cut has been thoroughly extinguished. The Bank of England is widely expected to raise interest rates to 4.0% from 3.75% this Thursday in response to mounting inflation pressure. This rise would mark the first time the central bank has raised borrowing costs since August 2023.
UK inflation rose more than expected in September to a near one-year high of 3.5%, driven by rising energy costs. This pressure is expected to compound this winter after Ofgem's energy price cap rose by 3.6% for a typical household on October 1. Analysts had previously anticipated strong house price growth, but economic pressures associated with the US-Iran War have rapidly shifted expectations toward sustained rate hikes.
The conflict has pushed back the prospect of meaningful mortgage rate relief.
Source: Emily Williams, Director of Residential Research at Savills (The Telegraph)
The central bank had previously held off raising rates in the wake of the war, with BoE Governor Andrew Bailey warning against rushing to judgment about inflation risks. However, this latest spike means securing a fixed rate now is essential risk management for homebuyers.
Sources: Office for National Statistics (ONS), Reuters, Financial Times, The Telegraph, and The Independent
Property Types: The House vs. Flat Divide
Beneath the headline averages, a two-tier property market has firmly established itself. Buyers are paying a premium for space and the security of a freehold, while flats are bearing the absolute brunt of the market slowdown.
Here is how the different property types performed over the 12 months leading up to August 2026:
- Semi-Detached Houses (+1.79%): Leading the market, the average semi-detached home has risen to £286,814.
- Terraced Houses (+1.51%): Driving strong demand, the average price is now £241,509.
- Detached Houses (+0.37%): The top of the market remains stable, reaching £461,962.
- Flats and Maisonettes (-2.78%): Flats are the only property type actively losing value, falling to £215,804.
This fall in value across the leasehold sector is mirrored exactly by the rise in headaches for owners and prospective buyers. Lenders are heavily scrutinising ground rent terms and insisting on strict mortgagee protection clauses. When combined with aggressive freeholder controls and escalating service charges, many flats are becoming borderline unmortgageable without significant legal remediation.
However, long-awaited regulatory relief may be on the horizon. Housing Secretary Angela Rayner has just announced new plans designed to protect leaseholders from "punitive hidden costs". Furthermore, these incoming regulations will require estate agents to obtain formal qualifications to operate, signalling a broader government push to professionalise the sector and protect consumers navigating these complex transactions.
As seen in The Negotiator
"We are seeing transactions stall on a daily basis because of delayed leasehold reforms and the sheer complexity of Building Safety Act compliance, ground rent clauses, lease terms and mortgagee protection clauses. Buyers are no longer just looking at the asking price, they are actively factoring in the legal risks and future liabilities."
Andrew Boast FMAAT, CEO of SAM Conveyancing
New Build Delivery & Planning Reforms
The call to expand equity loans to existing housing stock comes as the government falls severely behind on its construction targets. The number of new homes being built has fallen across almost all regions of the UK, according to figures from the National House Building Council (NHBC).
Since July 2024, exactly 250,520 new dwellings have been completed across seven quarters of published data. This leaves the current administration running at an estimated annual rate of just 143,154 homes, less than half of the 300,000 annual completions required to meet its manifesto commitment.
In an effort to stimulate residential construction and overcome bureaucratic delays, developers will now be able to pay a one-off nature recovery charge of £2,000 per property to receive fast-track planning approval. The industry hopes this will ease the supply bottlenecks that have continually suppressed new build completion figures, though experts warn that financial levies alone cannot replace fundamental market liquidity.
Sources: MHCLG Live Tables on House Building, NHBC, The Times, and SAM Conveyancing Research
Andrew Boast FMAAT
CEO of SAM Conveyancing
Housing Market Opinion
The October 2026 market proves that the era of aspirational pricing is over. Data from Savills predicts that average house prices will fall by 1.5% in 2027, marking the first time since the early 1990s that values have not risen for two consecutive years, with a meaningful recovery pushed back to 2028. The 3,000 price cuts happening every single day in September confirm that buyers are already aggressively enforcing this affordability ceiling.
This squeeze is cementing the two-tier nature of the current market. Buyers are deploying their restricted capital highly selectively. They are paying a premium for freehold houses while actively avoiding the escalating compliance liabilities of leasehold flats. Unless sellers of urban apartments price their properties aggressively to attract cash investors, they risk joining the vast majority of flat owners whose listings are stagnating past the 119-day mark.
Looking ahead to the Chancellor's Autumn Budget on 28 October, government intervention must be calculated carefully. The "Your first home" equity loan scheme has excellent potential to unblock the bottom of the property chain. However, as our own data analysis highlights, restricting this financial support exclusively to new developments will simply line the pockets of volume housebuilders while trapping young families in an artificial 40% new-build price premium.
To genuinely restore market liquidity before 2028, the Treasury must open this scheme to the secondhand market and peg the equity loans to independent RICS valuations. This approach would protect the taxpayer, bypass developer price inflation, and finally unfreeze the chains, allowing existing homeowners to trade up into the current surplus of available family homes.
Sources: Latest data from Gov.UK, Bank of England, UK House Price Index, ONS and Propertymark (NAEA).

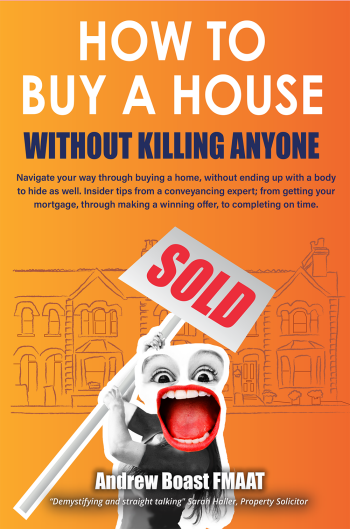
Without Killing Anyone
This book could be the difference between every mover’s dream, buying and moving into your new home stress free, or, stress, missed deadlines, legal disasters, building defects, and possibly the collapse of the whole transaction. (Costing you a small fortune, a head full of grey hairs, and, driving you to threaten the life of your solicitor, lender, co-owners, family, partner, or some combination of all five).
With more than two decades’ experience in the conveyancing sector and over 50,000 successful client moves under his belt, Andrew shares insider tips and advice to empower you as a buyer, giving you the tools to make the best decisions for your circumstances and ease the chaos.
Available on Amazon | Kindle | Paperback