September 2026 Housing Market Report: Modest Recovery amid Rising Costs


- The Price Gap: While Rightmove reported a 0.7% bump in average asking prices in September, Nationwide data shows completed house prices actually fell by 0.2%, with annual growth halving to 0.8%.
- First-Time Buyer Scheme Debate: Following the announcement of the government's "Your first home" equity loan scheme, property experts are urging Chancellor John Healey to open the policy to the secondhand market to prevent an artificial new-build price bubble.
- Regulatory Overhaul: Housing Secretary Angela Rayner has announced incoming plans to protect leaseholders from punitive hidden costs and mandate formal qualifications for estate agents.
- Autumn Budget Anticipation: Prime Minister Andy Burnham is expected to outline significant market interventions on 28 October, with industry pressure mounting for localised housing funding and permanent Stamp Duty relief for first-time buyers.
- Hawkish Central Bank: The Bank of England held the base rate at 3.75%, but rising motor fuel costs pushed inflation to 3.1%, prompting rate-setters to openly discuss a hike to 4.0%.
- The Flat Depreciation: Flats continue to actively lose value, falling 2.27% year-on-year, as buyers prioritise freehold houses to avoid mounting leasehold compliance headaches.
The UK property market is currently defined by a stark gap between seller expectations and buyer affordability. Data from Rightmove reveals that the average price of a property coming to market in September rose by 0.7%, or £2,441. This marks the first month-on-month increase in asking prices since May and aligns with recent findings from the Royal Institution of Chartered Surveyors (RICS), which reported that their house price balance rose to a five-month high in August.
However, this initial optimism is not translating into completed transactions. Fresh data from Nationwide shows that actual UK house prices fell by 0.2% in September, marking the fastest drop since May and leaving the average UK home valued at £274,251. Furthermore, annual house price growth halved, dropping from a 1.6% rise in August to just 0.8% in September.
This suppression in completed values is driven by severe economic uncertainty and the conflict in the Middle East, which continues to deter homebuyers. The number of homes available to purchase has now hit a 12-year high, while buyer enquiries remain 9% lower than this time last year. Buyers are active, but with such high stock levels and elevated borrowing costs, they are refusing to meet aspirational asking prices.
Activity has remained subdued in recent months due to an uncertain economic backdrop, higher mortgage rates and expectations for interest rate increases.
Source: Robert Gardner, Chief Economist at Nationwide Building Society
Where is the opportunity in today's market?
While the market absorbs high stock levels and stubborn borrowing costs, pragmatic home buyers can still find distinct tactical advantages:
- First-Time Buyers: The newly announced "Your first home" equity loan scheme will drastically lower the barrier to entry, allowing buyers with stable incomes to secure homes with just a 2.5% deposit.
- Cash Buyers & Investors: With flat values dropping and leasehold transactions stalling, cash buyers immune to strict lender stress tests hold unprecedented leverage to negotiate heavy discounts on urban apartments.
- Up-Sizers: Rightmove reports property listings have hit a 12-year high, which means buyers moving up the ladder have maximum choice and the negotiating power to demand realistic pricing from vendors eager to complete before year-end.
Sources: Rightmove, Nationwide, and Reuters
Property prices and sales volumes
England & Wales
The latest Land Registry data confirms that transacted values have maintained slight annual growth despite high borrowing costs. In June 2026, the average property price in England & Wales stood at £287,949, a 1.8% year-on-year increase compared to June 2025 (£282,900).
The average price for first-time buyers reached £241,257, up 1.8% annually. Meanwhile, owner-occupiers purchased at an average of £350,491 (up 1.8%), and cash buyers at £274,141 (up 1.4%).
Beneath the national figures lies a pronounced geographic divergence. Commuter belts on the periphery of northern hubs such as Manchester and Glasgow (notably Rochdale and Falkirk) saw asking prices rise 1.5% year-on-year, driven by buyers seeking value away from southern price caps.
Mortgage Rates
Official quoted household interest rates for August 2026 confirm the reality on the ground for borrowers: refinancing remains a significant financial hurdle.
Analysis shows that UK homeowners are now paying an average of £840 more per year when refinancing their mortgages. This friction is severely compressing the onward purchasing power of existing homeowners, meaning those looking to trade up the property ladder must heavily subsidise their move by driving a hard bargain on their onward purchase.
For those looking to secure new borrowing, the recent spike in wholesale swap rates means high street lenders are actively pulling their most competitive fixed products. Borrowers are strongly advised to lock in formal offers immediately to protect their purchasing budgets against further repricing.
| Mortgage Product | August 2026 | July 2026 | August 2025 |
|---|---|---|---|
| 2 Year Fixed (75% LTV) | 4.92% | 4.79% | 4.10% |
| 2 Year Fixed (90% LTV) | 5.16% | 5.07% | 4.55% |
| 5 Year Fixed (75% LTV) | 4.78% | 4.58% | 4.11% |
| 5 Year Fixed (90% LTV) | 4.95% | 4.85% | 4.43% |
Sources: Financial Times and Bank of England
Will mortgage rates go down in Autumn 2026?
Any remaining optimism for an Autumn rate cut has been thoroughly extinguished. The Bank of England held interest rates at 3.75% for a sixth consecutive meeting, but the rhetoric has shifted sharply toward future hikes. Following surges in global oil and gas prices, UK inflation jumped to 3.1% in August, reaching its highest point since March. Motor fuel alone has seen a 23% cost increase over the last year.
This pressure is compounding at the supermarket checkout. The Food and Drink Federation forecasts that food inflation will reach 4% by Christmas and peak at 6.4% in July next year, driven by the ongoing Middle East conflict and extreme weather across Europe.
The longer this volatility persists, the bigger the impact it will have on inflation and the more likely it is we will need to raise the Bank rate.
Source: Andrew Bailey, Governor of the Bank of England (The Times)
Senior Monetary Policy Committee members Clare Lombardelli and Sarah Breeden have both raised the immediate prospect of voting to push borrowing costs to 4.0%. In response, the Bank has also announced a surprise change to its bond-selling programme, planning to offload £20 billion a year to the Treasury. For homebuyers, this means securing a fixed rate now is essential risk management.
Sources: Office for National Statistics (ONS), Financial Times, and Bloomberg
Property Types: The House vs. Flat Divide
Beneath the headline averages, a two-tier property market has firmly established itself. Buyers are paying a significant premium for space and the security of a freehold, while flats are bearing the absolute brunt of the market slowdown.
Here is how the different property types performed over the 12 months leading up to June 2026:
- Semi-Detached Houses (+3.16%): Leading the market, the average semi-detached home has risen to £285,618.
- Terraced Houses (+2.76%): Driving strong demand, the average price is now £240,147.
- Detached Houses (+1.98%): The top of the market remains stable, reaching £463,547.
- Flats and Maisonettes (-2.27%): Flats are the only property type actively losing value, falling to £216,246. Over a five-year period, flats are down 1.56%.
This fall in value across the leasehold sector is mirrored exactly by the rise in headaches for owners and prospective buyers. Lenders are heavily scrutinising ground rent terms and insisting on strict mortgagee protection clauses. When combined with aggressive freeholder controls and escalating service charges, many flats are becoming borderline unmortgageable without significant legal remediation.
However, long-awaited regulatory relief may be on the horizon. Housing Secretary Angela Rayner has just announced new plans designed to protect leaseholders from "punitive hidden costs". Furthermore, these incoming regulations will require estate agents to obtain formal qualifications to operate, signalling a broader government push to professionalise the sector and protect consumers navigating these complex transactions.
As seen in The Negotiator
"We are seeing transactions stall on a daily basis because of delayed leasehold reforms and the sheer complexity of Building Safety Act compliance, ground rent clauses, lease terms and mortgagee protection clauses. Buyers are no longer just looking at the asking price, they are actively factoring in the legal risks and future liabilities."
Andrew Boast FMAAT, CEO of SAM Conveyancing
First-Time Buyers & The New-Build Premium Trap
The government is preparing to announce full details of its flagship "Your first home" programme in Chancellor John Healey's Autumn Budget on 28 October 2026. The policy, championed by Prime Minister Andy Burnham, will offer first-time buyers in England a 20% government equity loan with a 2.5% deposit, specifically targeting those who cannot rely on family financial assistance.
This initiative directly addresses a growing affordability crisis. According to a recent Freedom of Information request submitted by money app Plum, the number of first-time buyers forced to borrow more than 4.5 times their income increased by two-thirds in 2025.
However, SAM Conveyancing is urging the Treasury to expand the scheme to the secondhand market to avoid repeating the failures of the previous Help to Buy programme. Official figures show that while Help to Buy supported 328,000 first-time buyers between 2013 and 2023, it funnelled 11% of the entry-level market into a captive environment, inflating new-build prices by 70.1%.
Today, buyers face an immense financial penalty for purchasing new stock. HM Land Registry figures reveal that new-builds now command a 40.1% premium over established properties, averaging £396,889 compared to £283,194 for an existing home.
By opening the 20% equity loan to established freehold houses and existing flats, SAM Conveyancing argues the government could unfreeze the second-stepper chain. This would allow first-time buyers to purchase existing homes and free current owners to step up to larger properties. To safeguard taxpayers and prevent sellers from artificially inflating prices, equity loans on secondhand homes should be strictly pegged to an independent valuation from a RICS-regulated surveyor at the point of purchase.
Mortgage Introducer: Extend 'Your First Home' scheme to existing homes, say property experts
"Help to Buy was presented as a cure for Britain's housing crisis, but the data proves it functioned primarily as a price-support mechanism for volume housebuilders. Developers simply baked that extra purchasing power straight into their asking prices. If Chancellor John Healey genuinely wants to get Britain moving, he should let first-time buyers use this scheme on any property they choose."
Andrew Boast FMAAT, CEO of SAM Conveyancing
Autumn Budget Preview: What to Expect
Beyond the equity loan scheme, property professionals are closely monitoring Prime Minister Andy Burnham and Chancellor John Healey for further market interventions on 28 October.
Burnham is expected to outline plans to grant city mayors a share of income tax revenue, a move designed to drive decentralised, localised housing investment and infrastructure projects. Concurrently, industry leaders are mounting significant pressure on the Treasury to announce a permanent abolition of Stamp Duty Land Tax (SDLT) for entry-level homes. If the administration combines targeted SDLT relief with a well-executed equity loan scheme and localised funding, it could provide the exact stimulus required to unfreeze the lower rungs of the property ladder before the end of the year.
New Build Delivery & Planning Reforms
The call to expand equity loans to existing housing stock comes as the government falls severely behind on its construction targets. Analysis of official housebuilding statistics indicates that the government's pledge to build 1.5 million homes over five years is severely off track.
Since July 2024, exactly 250,520 new dwellings have been completed across seven quarters of published data. This leaves the current administration running at an estimated annual rate of just 143,154 homes, less than half of the 300,000 annual completions required to meet its manifesto commitment.
In an effort to stimulate residential construction and overcome bureaucratic delays, developers will now be able to pay a one-off nature recovery charge of £2,000 per property to receive fast-track planning approval. The industry hopes this will ease the supply bottlenecks that have continually suppressed new build completion figures, though experts warn that financial levies alone cannot replace fundamental market liquidity.
Sources: MHCLG Live Tables on House Building, Financial Times, and SAM Conveyancing Research
Andrew Boast FMAAT
CEO of SAM Conveyancing
Housing Market Opinion
The September 2026 market presents a highly complex landscape for property professionals and home movers alike. The headline data reveals a clear standoff between seller aspiration and buyer reality. While vendors feel confident enough to push asking prices up by 0.7%, buyers simply do not have the borrowing capacity to meet them, resulting in actual completed sale prices dropping by 0.2%.
This affordability ceiling is cementing the two-tier nature of the current market. Buyers are deploying their restricted capital highly selectively. They are paying a premium for freehold houses while actively avoiding the escalating compliance liabilities of leasehold flats. Unless sellers of urban apartments price their properties aggressively to attract cash investors, they risk joining the vast majority of flat owners whose listings are stagnating past the six-month mark.
Looking ahead to the Chancellor's Autumn Budget, government intervention must be calculated carefully. The "Your first home" equity loan scheme has excellent potential to unblock the bottom of the property chain. However, as our own data analysis highlights, restricting this financial support exclusively to new developments will simply line the pockets of volume housebuilders while trapping young families in an artificial 40% new-build price premium.
To genuinely restore market liquidity, the Treasury must open this scheme to the secondhand market and peg the equity loans to independent RICS valuations. This approach would protect the taxpayer, bypass developer price inflation, and finally unfreeze the chains so existing homeowners can trade up into the current surplus of available family homes.
Sources: Latest data from - Gov.UK, Bank of England, UK House Price Index, ONS and Propertymark (NAEA).

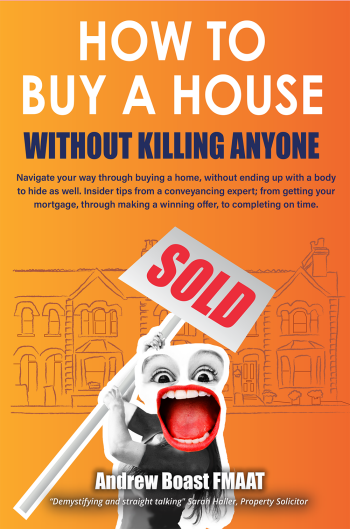
Without Killing Anyone
This book could be the difference between every mover’s dream, buying and moving into your new home stress free, or, stress, missed deadlines, legal disasters, building defects, and possibly the collapse of the whole transaction. (Costing you a small fortune, a head full of grey hairs, and, driving you to threaten the life of your solicitor, lender, co-owners, family, partner, or some combination of all five).
With more than two decades’ experience in the conveyancing sector and over 50,000 successful client moves under his belt, Andrew shares insider tips and advice to empower you as a buyer, giving you the tools to make the best decisions for your circumstances and ease the chaos.
Available on Amazon | Kindle | Paperback