How to Avoid Stamp Duty on Second Home

Buying a second home will usually mean paying the higher rates of Stamp Duty Land Tax (SDLT), which adds thousands of pounds to your purchase costs. However, the higher rates do not apply in every situation. If you are replacing your main residence, for example, you may be able to avoid the higher rates or reclaim them after selling your previous home.
This guide explains when the higher rates apply, how much second-home stamp duty could cost, the legitimate ways you may avoid or reclaim the higher rates, how the refund process works and what to check before you buy.
- Higher rates: Buying an additional residential property will usually mean paying the higher rates of SDLT. Additional properties are usually subject to a 5% rate, depending on the portion of the purchase price. This is on top of the standard rate.
- Replacing your home: If you are replacing your main residence, you may avoid the higher rates if you sell your previous home before or on the day you buy.
- Refunds: If you buy your new home before selling your old one, you will usually pay the higher rates upfront, but may be able to reclaim the higher-rate element after selling your previous main residence.
- Check before buying: Property owned overseas, joint purchases, spouses and civil partners, companies, trusts and partnerships can all affect the SDLT position.
How can I avoid stamp duty on a second property?
There is no general loophole that allows you to buy a second home without paying SDLT. Instead, whether you pay the higher rates depends on your property ownership and circumstances at the time of purchase.
The most common ways you may avoid or reclaim the higher rates include:
- Selling your previous main residence before or on the same day as buying your new home.
- Buying your new home first and claiming a refund after selling your previous main residence.
- Buying a property or property interest that is excluded from the higher-rate rules.
- In some circumstances, structuring a purchase so that someone helping with the mortgage does not acquire a beneficial interest in the property.
- Unmarried couples buying a home before marriage.
To avoid the second home stamp duty, you can exclude anyone with an interest from the legal title, use a joint mortgage sole proprietor mortgage, transfer from a partnership to a limited company or purchase for less than £40,000.
Exclude anyone from the legal title who owns an interest in another property
If you are buying a property with someone who already owns another residential property, putting both names on the legal title can affect whether the higher rates of SDLT apply. For joint purchasers, the higher rates may apply to the entire transaction if any purchaser would be liable for them.
If you are married, it doesn't matter whose name is on the title. As long as you or your spouse owns an interest in another property, the additional rate is applicable - SDLT - higher rates for additional dwellings: purchasers with a spouse or civil partner.
However, HMRC says that a person who is named as a legal owner but has absolutely no beneficial interest may not be treated as a joint purchaser for the higher-rate rules. This must be evidenced in writing. If that person is entitled to a share of the sale proceeds, rental income or occupation of the property, they are likely to have a beneficial interest.
You cannot simply leave someone off the title to avoid SDLT
If you are married or in a civil partnership and living together, your spouse or civil partner's property ownership can still be taken into account even if they are not named as a purchaser.
Joint Mortgage Sole Proprietor mortgage
You will be named on the mortgage but not the legal title, allowing you to avoid paying stamp duty on second homes. This allows you to help your child, for example, purchase a property.
This is not something to treat as a simple SDLT loophole. The legal and tax position depends on the actual arrangement, including who owns the property, who benefits from it and what rights the non-owner has. If you are considering a JBSP arrangement or lending money towards someone else's purchase, get the structure checked before proceeding.
Expert Tip: A loan instead of beneficial interest
Having a beneficial interest will trigger second home stamp duty, but having a loan won't. Could invest in a property, have an interest in a loan, get paid back in the future, and not trigger second home stamp duty. Downside is all loans will be declarable to a mortgage lender, which will affect your mortgageability.
CEO of SAM Conveyancing
Transfer the property from a partnership to a limited company
If your property is part of a partnership, you can transfer it to a limited company without having to pay stamp duty on a second home. We explain this further in our article - How do I transfer a partnership to a limited company with no SDLT?
However, it is important to note that companies can actually be subject to the 5% higher-rate surcharge when buying residential property. Also, a separate 17% SDLT rate can also apply to corporate bodies buying residential properties costing over £500,000, although specific reliefs and exclusions can apply.
Buy a property for under £40,000
Stamp duty higher rates only apply to properties £40,000 and over. The challenge is that if your intention is to have an interest in the property and you already own another property, the second-home stamp duty applies. You can, however, draft a loan agreement to protect your investment, which isn't considered an interest in the property and as such doesn't attract the additional rate of stamp duty.
If your intention is to have a benefit/interest from the property, then there is no way to avoid second home stamp duty if you own another property and have no intention of selling it to make the new property your main residence.
Looking for a Stamp Duty loophole?
There isn't a "loophole" to avoid paying Stamp Duty, but there are ways you can effectively reduce the amount you pay on a property purchase or a transfer.
Which second homes are exempt from stamp duty?
You can avoid paying stamp duty on second homes if your property is:
- worth less than £40,000
- easy to move around (i.e. boats or caravans)
- a combination of residential and non-residential (building with upstairs flat and shop on the ground floor)
- falls within certain leasehold exclusions
How much is stamp duty on a second home?
The higher rates of Stamp Duty Land Tax (SDLT) are currently 5 percentage points above the standard residential rates. The amount you pay depends on the purchase price and the SDLT rates that apply to each portion of the property value.
For example, an additional residential property bought for £300,000 is currently subject to SDLT at 5% on the first £125,000, 7% on the next £125,000 and 10% on the remaining £50,000, giving a total SDLT bill of £20,000.
|
Property Price
|
Standard Rate of Stamp Duty
|
Additional Home Rate of 5% & Standard Rate
|
Non UK Resident Rate
|
|
£0 - £125,000
|
0%
|
5% (from £40,001)
|
2%
|
|
£125,001 - £250,000
|
2%
|
7%
|
2%
|
|
£250,001 - £925,000
|
5%
|
10%
|
2%
|
|
£925,001 - £1.5 million
|
10%
|
15%
|
2%
|
|
Over £1.5 million
|
12%
|
17%
|
2%
|
Expert Tip: Multiple dwellings and the end of Multiple Dwellings Relief
Multiple Dwellings Relief (MDR) was abolished for most transactions completed or substantially performed on or after 1 June 2024. However, where six or more residential properties are bought in a single transaction, the purchase is generally treated as non-residential for SDLT purposes.
If you are buying multiple properties, do not assume that the normal second-home rules apply. The SDLT calculation can be considerably more complicated.
Partner & Head of Conveyancing
Second home stamp duty calculator
Use our stamp duty calculator to estimate how much SDLT you could pay based on your purchase price and circumstances.
How to avoid stamp duty on a second home with a loan?
A genuine loan secured against a property is different from owning a beneficial interest in that property. For SDLT purposes, a security interest is treated as an exempt interest. Section 48 of the Finance Act 2003 defines a security interest as an interest or right held to secure payment of money or the performance of an obligation.
However, the arrangement must be a true debt. Simply labelling an equity share or ownership stake as a "loan" will not prevent HMRC from applying the 5% additional property SDLT surcharge.
Expert Tip: What to know about using a loan
If you're considering lending money to help someone buy a property, the way the arrangement actually works matters more than what the paperwork calls it. Simply describing an arrangement as a “loan” does not necessarily mean you have no beneficial interest in the property or that the SDLT higher rates will not apply.
Before exchanging contracts, get legal and tax advice on the proposed structure. For example, a Joint Borrower Sole Proprietor (JBSP) mortgage differs from contributing money in exchange for an unrecorded share of the property. Understanding the distinction can help you avoid an unexpected SDLT liability or higher-rate surcharge later.
Partner & Conveyancing Solicitor
Rules for structuring an exempt loan
To ensure a financial contribution does not trigger the 5% second home SDLT surcharge:
- Legal ownership: The buyer alone must be registered on the Land Registry title deeds.
- No equity or profit rights: The lender receives only repaid principal plus interest. They cannot receive a share of property value growth or rental income.
- No occupation rights: The loan must not grant the lender a right to live in or use the property.
- Formal written agreement: A deed or loan agreement must formally record the transaction as a pure debt.
- Suitable for loans to not trigger second home stamp duty.
- Drafted by a specialist solicitor.
- Completed within 5 working days.
- Standard document for a fixed fee of £399 INC VAT
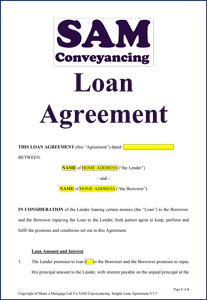
Case study: Avoiding the 5% second home SDLT surcharge with a JBSP loan
Jane was purchasing a residential home for £500,000. Her father, Peter, already owned a home and wanted to assist her without triggering the 5% second home Stamp Duty Land Tax (SDLT) surcharge. To achieve this, Peter took out a Joint Borrower Sole Proprietor (JBSP) mortgage for £350,000 and provided a £150,000 deposit under a formal draft loan agreement specifying full repayment of principal plus interest.
Under the structure, Jane became the 100% legal and beneficial owner of the deeds. Because Peter held no legal title under the JBSP structure, HMRC ignored his personal homeownership status. Furthermore, because his £150,000 deposit contribution was structured as a pure repayable debt with no capital growth or occupation rights, it qualified as an exempt security interest under Section 48 of the Finance Act 2003.
The takeaway: A genuine loan is distinct from holding an equity stake in a property. By properly documenting a financial contribution as a debt and using a JBSP structure, family members can assist with property purchases without incurring the 5% additional property surcharge.
Ensure loan agreements and property ownership deeds are legally verified prior to exchange of contracts to prevent HMRC treating the funds as an unrecorded equity share.
When do you pay Stamp Duty Land Tax?
If any party acquires an interest or a greater interest in land, Stamp Duty Land Tax (SDLT) or Land Transaction Tax will be payable by reference to any chargeable consideration given for it. Chargeable consideration is defined in the Finance Act 2003, Schedule 4, Stamp duty land tax: chargeable consideration and confirmed by HMRC with examples.
Your SDLT return generally needs to be sent to HMRC and the SDLT paid within 14 days of the effective date of the transaction. For most straightforward property purchases, the effective date is completion.
Your conveyancer will normally deal with the SDLT return and payment as part of the conveyancing process. This means you should establish your likely SDLT liability before completion, particularly if you are buying an additional property and need to budget for the higher rates.
Can you claim back stamp duty on a second home?
If any of the parties purchasing a property own an interest in any other property around the world, then the higher rates of SDLT are payable. However, if you sell your previous main residence within 36 months of buying your new home, you may be able to claim a refund of the higher-rate element. For properties sold on or after 29 October 2018, HMRC must receive the refund claim by the later of 12 months after the sale or 12 months after the SDLT return for the new home is filed.
If you are forced to pay it, however, once you sell the previous main residence, you can claim a second home stamp duty refund.
Need help with Stamp Duty on a second home?
Our conveyancing specialists can help you understand your Stamp Duty position, including whether you could avoid or reclaim the higher rates.
Frequently asked questions
Andrew Boast FMAAT is a qualified accountant, conveyancing specialist and author with over 25 years of experience in the UK property sector. Since beginning his career in 2000 within established SRA and CLC-regulated conveyancing solicitor firms, Andrew has overseen the legal journeys of more than 75,000 clients.
He is the self-published author of the first-time buyer guide: How to Buy a House Without Killing Anyone, and a frequent contributor to mainstream UK media on legislative updates, property law, first-time buyer guides, conveyancing best practices, and stamp duty changes. Andrew specialises in resolving complex title issues, property conflict disputes, and property tax options, streamlining the enquiry process to reduce transaction times and maintaining a client-friendly focus.
Amanda Ambler is a highly accomplished conveyancing specialist with over 15 years of dedicated experience across residential property law, legal compliance, and practice management. Having held senior roles, including Head of Legal Practice and Head of Conveyancing at established UK law firms, Amanda possesses a profound, hands-on understanding of the technical intricacies of the property market.
As the designated Legal Content Reviewer for SAM Conveyancing, Amanda ensures that every guide, legal update, and resource published meets the absolute highest standards of accuracy, regulatory compliance, and factual integrity. Her rigorous review process guarantees that complex property legislation and industry processes are communicated clearly, transparently, and safely for home buyers and sellers alike.