
Structural Movement in a House; what's normal?

Discovering structural movement in a house is one of the biggest fears for any homebuyer or property owner. Whether a RICS survey has flagged expanding cracks during the conveyancing process, or you are worried about subsidence affecting your property's value, understanding the root cause is critical.
While minor settlement is often perfectly normal, severe downward movement (subsidence) or upward expansion (heave) can compromise the building's safety and lead to outright mortgage rejections. In this expert guide, we explain the different types of structural movement, how to identify the warning signs, and exactly when you need to escalate the issue to a specialist structural engineer.
For more specific guidance on common causes and warning signs, read our dedicated guides on whether wisteria can cause subsidence and when to worry about cracks in brickwork.
- Structural movement is common, but forms like subsidence (downward movement of foundations) can pose major risks to a property's integrity.
- Look out for expanding diagonal cracks wider than 3mm (roughly the width of a 50p coin), sticking doors, and rippling wallpaper.
- A RICS surveyor will flag visible signs of concerning movement during a standard Home Survey, which is required by most mortgage lenders.
- If subsidence is suspected, a structural engineer must conduct a non-intrusive or intrusive inspection to recommend repairs such as underpinning.
- You can still buy and sell a house with movement, but you should be prepared to renegotiate the price to account for necessary structural work.
What is structural movement?
Structural movement refers to any shifting in the physical structure of a building. While some settling is natural, severe movement compromises the safety and value of the home. There are many kinds of structural movement, including:
- Subsidence: The lowering and shrinking of the ground under a house, causing the property’s foundations to sink. As foundations shift downward, it produces movement in the upper parts of the property, pulling walls apart and causing severe cracking.
- Settlement: The disruption or distortion of parts of the building due to shrinkage or unequal compression under its own weight (usually occurring shortly after construction).
- Heave: The opposite of subsidence. Heave is when soil expands, pushing the ground beneath the house upward. This frequently happens in clay soil where the ground swells when wet.
- Sway: The movement of a building from side to side. Most homes in the UK are non-sway structures. You do not want a residential building to sway unless it is specifically designed to withstand the movement (like a modern skyscraper).
- Bouncy floors: Floor deflection occurs when floor joists are too small or spaced too far apart to support the load above them.
- Bulging walls: Walls can bow vertically due to failing ties or vibrations from heavy traffic. This is dangerous as the floor space can widen, leaving joists too short and unstable.
- Expansion & Contraction: Materials expand with temperature changes or damp levels, and contract when drying out (such as 'green' wood shrinking).


What causes structural movement and subsidence?
External factors and ground conditions
A perfectly constructed house will still face severe issues if the ground on which it is built moves. Properties built before 1965 with shallow foundations are at a much higher risk. The primary external causes include:
- Trees Close to Property: Large trees with deep roots draw massive amounts of water from the soil, making it loose. Roots can also physically grow into gaps in foundations. Keeping trees well-pruned helps mitigate this risk.
- Clay Sub-Soils: In dry weather, moisture is removed from clay soil, causing it to shrink dramatically and destabilising the foundations above.
- Water Leaking: Burst drains or leaking mains water can physically wash away the soil supporting the foundations. This is a particular problem when the ground is made of sand, gravel, or chalk.
Construction materials
If materials lack adequate strength or are incompatible, structural stability is compromised. For example, replacing a steel ridge beam with a timber beam of the same size will fail under the weight, causing immediate damage.
The Calcium Silicate Brick Problem
Sometimes, calcium silicate bricks are used in house building. These bricks have 1.5 times the thermal expansion of standard clay bricks. If constructors fail to use weaker mortar and include additional movement joints, the mortar becomes stronger than the bricks. As temperatures rise and the bricks expand, they crack and shatter against the rigid mortar, allowing water ingress and causing severe structural decay.
Construction method
If a building is not properly tied together, it will move. Common construction failures include:
- Internal walls not being properly bonded to external walls.
- Missing or failing lintels above doors and windows.
- The weight of the roof pushing external walls outward because it is not properly tied at the ceiling level (known as roof spread).
- Load-bearing structures, such as chimney breasts, being removed without proper steel reinforcement.
UK Subsidence & Sinkhole Hotspots
Certain regions in England are highly susceptible to sudden ground movement and sinkholes due to historical industry and unique geology. For instance, areas across St Albans and the wider Hertfordshire region have experienced sudden sinkholes due to historical chalk mining and deep clay extraction. Similarly, buyers in Cheshire must legally obtain a Cheshire Salt Search to check for brine mining subsidence risk. If you are buying in an area with a history of mining (coal, chalk, or salt), professional environmental searches are mandatory.
How can I spot the signs of movement?
Cracks are the most obvious sign, but you must know how to distinguish standard settling from severe subsidence.
- The 50p Coin Test: If a diagonal crack is wider than 3mm (the thickness of a 50p coin) and expands over time, it is a severe warning sign of subsidence.
- Sticking doors and windows: If frames warp as the walls shift, doors and windows will no longer close properly.
- Wallpaper ripples: When interior walls warp and move, the wallpaper often creases or lifts away at the seams.
- External leaning: Gappy window frames, outward-leaning walls, and cracked chimney structures indicate significant differential movement.
How much movement in a house is normal?
Some movement is completely normal. Long before modern engineers calculated shrinkage, master joiners built houses from green oak, knowing it would shrink and settle as it aged. Hairline cracks in plaster (under 3mm) are very common, especially in new build properties, as the plaster dries out.
However, cracks over 5mm allow water in, causing dampness and further decay. Beyond 15mm, you will see severely distorted door frames, sloping floors, and structural failures requiring masonry replacement.
Minor structural movement is normal and shouldn't put you off of buying a home. If the issue is (or looks like it might be) extensive, then you're right to be questioning if the purchase is right for you. If you're willing to take on a bit of a project, you can proceed, with caution!
We recommend you always get a house survey when buying a home; your chartered surveyor will note any visible signs of structural movement and may recommend an intrusive inspection from a structural engineer if they believe further investigation is required.
You should not proceed with the purchase until the full extent of the issue has been discovered, as structural movement can cost anywhere from a couple of hundred pounds for a patch job to somewhere in the region of £40,000 to underpin the whole building.
Any estimated costs can be negotiated off the sale price, with support from your surveyor.
You may, however, still have a problem with your lender, as they are unlikely to grant you the mortgage funds if they aren't satisfied that the property is safe. If you are buying with a mortgage and the intention to remedy the problems after purchase, you should speak to a broker about what mortgage products may be suitable for you.
Structural movement doesn't mean you won't be able to sell your house, but you should be prepared that it will be a bit trickier. First and foremost: You must never lie or misrepresent the property to the seller. Trying to cover up any serious issues is misrepresentation, which can result in a big lawsuit.
You should keep a record of any builders' assessments, structural survey or engineer's reports that you have had, and be upfront with your buyer, who will understandably want the sale price to reflect the risk they're taking on, if they go ahead and buy. If the structural movement is superficial, they will need to carry out surveys of their own to satisfy themselves (and their lender) that there is no risk.
If the problem is significant and you're not willing to come down on the sale price, you may have to look into getting the issue fixed yourself.
Even if you do come down on price, you may be unable to sell to a buyer with a mortgage, as the mortgage lender is unlikely to grant the money unless they are satisfied that the property (and their investment) is safe. A cash buyer may be willing to take the risk, for the right price.
Your options are fairly simple: either get the problem fixed or be prepared to accept a lower sale price to reflect the higher risk of buying a house with structural movement.
How to check for movement: Surveyors vs Engineers
There are various ways to check whether a property is adversely affected by current or historic movement.
Stage 1: Desktop Subsidence Reports & Searches
During conveyancing, environmental searches identify if the property sits on clay soil, in a historical mining area, or in a postcode at high risk of ground movement. This desk-based data highlights risk but does not physically confirm if the specific house is moving.
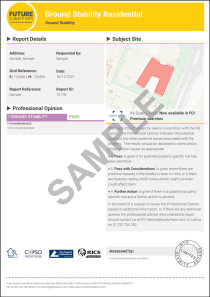
Do you need a Subsidence Report?
Order a subsidence search and put your mind at ease.
- Check for subsidence, landslide risks, and geology, mining and other hazards in the surrounding area.
- Find any damage claims for subsidence on your property and the surrounding area.
- Report delivered within 2 working hours.
- Fixed fee of £45 INC VAT.
Stage 2: The RICS House Survey
When buying a home in England & Wales, a stage of the conveyancing process is to buy a RICS Level 2 or Level 3 Home Survey. The surveyor conducts a visual inspection and will flag any visible signs of structural movement. If a mortgage valuer or your RICS surveyor suspects subsidence, they will place a retention on the mortgage and require a specialist structural engineer's report before lending you the money.
- We offer RICS Level 2 or 3 Home Surveys.
- National coverage with local RICS surveyors.
- Same week availability.
- Reports delivered within 5 working days.
Stage 3: The Structural Engineer Inspection
Where you have a RICS-surveyors report, such as a mortgage valuation, or a Level 2 or 3 Home Survey, or if the signs are severe, you must instruct a qualified structural engineer to inspect the property. They offer two types of assessment:
- Non-Intrusive Inspection (From £600): The engineer conducts a thorough visual assessment of the load-bearing elements and crack patterns to determine if the movement is historic (settled) or progressive (active subsidence). Where no movement is found, they can write a letter of comfort that a buyer can provide to their mortgage lender confirming there is no movement.
- Intrusive Inspection (From £600 + builder costs): Only required if active subsidence is confirmed. The engineer works alongside a builder to dig trial pits, exposing the foundations to find exactly what is causing the failure and precisely how to stabilise it.
- Specialist structural engineers for subsidence.
- Offering surveys for mortgage lenders, or for homeowners
- National network of local surveyors.
- Competitive prices.
Recent major sinkholes in England & Wales
While minor subsidence is a common property issue, sudden ground collapses, or sinkholes, are much more severe. These typically occur in areas with underlying soluble rock (such as chalk, limestone, or gypsum) or above historical, undocumented mine workings. Here are some of the most notable occurrences:
- St Albans, Hertfordshire: One of the most famous residential sinkholes occurred in Fontmell Close when a 20-metre-wide, 10-metre-deep hole opened across a suburban street, forcing the immediate evacuation of several families. Investigations revealed it was caused by a historical, unmapped chalk mine that collapsed following heavy rain and a suspected water leak.
- Ripon, North Yorkshire: Ripon is considered one of the UK's most active sinkhole hotspots due to its underlying Permian gypsum bedrock, which dissolves rapidly in groundwater. The city has experienced multiple major collapses, including significant residential sinkholes opening up in gardens and beneath properties over the last decade.
- High Wycombe, Buckinghamshire: A 30-foot-deep sinkhole suddenly opened in a residential driveway, completely swallowing a parked car. Like St Albans, the Buckinghamshire area sits heavily on chalk beds where historical brickmaking and chalk mining have left hidden voids vulnerable to sudden collapse.
- Mancunian Way, Manchester: Sinkholes do not just affect rural or suburban properties. A 40-foot-deep crater appeared in the carriageway of this major urban road after torrential rain caused a collapsed sewer, highlighting how failing underground infrastructure can erode the supporting soil beneath the surface.
- Skewen, Neath Port Talbot (Wales): While technically a mine water blowout rather than a traditional sinkhole, a sudden collapse of historical mine shafts beneath the village released torrents of water and caused severe ground instability, forcing the evacuation of over 80 residents and highlighting the risks of building over legacy coal mines.
Fixing the issue: Underpinning & costs
The good news is that roughly only 10% of subsidence-affected properties actually require full underpinning. If tree roots or leaking drains are the cause, removing the tree or fixing the pipe often halts the movement.
If the foundations have failed completely, underpinning is required. This involves excavating below the existing foundations and installing new concrete depth, piers, piles, or jacks. Depending on the property size and severity, underpinning costs range heavily from £5,000 to £80,000.
Modern alternatives to traditional underpinning include Jet Grouting, where chemical resins are injected into the ground beneath the house, expanding to turn loose soil into solid, stable aggregate.
Andrew Boast FMAAT is a qualified accountant, conveyancing specialist and author with over 25 years of experience in the UK property sector. Since beginning his career in 2000 within established SRA and CLC-regulated conveyancing solicitor firms, Andrew has overseen the legal journeys of more than 75,000 clients.
He is the self-published author of the first-time buyer guide: How to Buy a House Without Killing Anyone, and a frequent contributor to mainstream UK media on legislative updates, property law, first-time buyer guides, conveyancing best practices, and stamp duty changes. Andrew specialises in resolving complex title issues, property conflict disputes, and property tax options, streamlining the enquiry process to reduce transaction times and maintaining a client-friendly focus.
Amanda Ambler is a highly accomplished conveyancing specialist with over 15 years of dedicated experience across residential property law, legal compliance, and practice management. Having held senior roles, including Head of Legal Practice and Head of Conveyancing at established UK law firms, Amanda possesses a profound, hands-on understanding of the technical intricacies of the property market.
As the designated Legal Content Reviewer for SAM Conveyancing, Amanda ensures that every guide, legal update, and resource published meets the absolute highest standards of accuracy, regulatory compliance, and factual integrity. Her rigorous review process guarantees that complex property legislation and industry processes are communicated clearly, transparently, and safely for home buyers and sellers alike.